A Recovery Week With Yields Back Above 5%
SPY gained 2.59% in the week to November 13 and QQQ gained 3.63%, recovering from the prior Thursday’s selloff. The 10-year yield finished Friday at 5.15% after October CPI rose 0.4%. NVIDIA fell another 12.75% on the week. The VIX closed at 19.30, down from 25.64.
Weekly changes run from the November 6 close to the November 13 close.
Weekly Market Data (week ending November 13, 2026)
The stock table leads with the weekly change; Friday’s daily change is there for context. Macro rows use each indicator’s own as-of date. October CPI and October jobs are both in. Wednesday, November 11, was Veterans Day: stocks traded and the Treasury market was closed. This analysis was published on November 15 and uses only data available at Friday, November 13’s close.
| Ticker | Week-Ending Close (USD) | Weekly % Change | Friday Daily % |
|---|---|---|---|
| SPY | 754.37 | +2.59% | -0.36% |
| QQQ | 679.89 | +3.63% | -1.20% |
| AAPL | 356.27 | +4.14% | +0.39% |
| MSFT | 523.88 | -1.27% | +0.17% |
| NVDA | 162.85 | -12.75% | -2.01% |
| TSLA | 390.22 | +8.93% | -1.82% |
| Indicator | Latest Value | As Of | Weekly % Change |
|---|---|---|---|
| 10-Year Treasury Yield (^TNX) | 5.15% | 2026-11-13 | +6.07% |
| 10-Year Treasury (FRED DGS10) | 5.10% | 2026-11-12 | — |
| 2-Year Treasury (FRED DGS2) | 4.86% | 2026-11-12 | — |
| VIX (CBOE Volatility Index) | 19.30 | 2026-11-13 | -24.73% |
| US Dollar Index (DX-Y.NYB) | 103.41 | 2026-11-13 | +1.09% |
| WTI Crude Oil (CL=F) | $88.56 | 2026-11-13 | -2.50% |
| 30-Year Mortgage Rate (MORTGAGE30US) | 7.11% | 2026-11-12 | — |
| Effective Fed Funds Rate (DFF) | 3.88% | 2026-11-12 | — |
| Unemployment Rate (UNRATE) | 4.1% | 2026-10-01 | — |
| Nonfarm Payrolls (PAYEMS) | +165K | 2026-10-01 | — |
| CPI Index (CPIAUCSL) | 337.476 | 2026-10-01 | — |
SPY vs QQQ: Both Recovered From Last Thursday
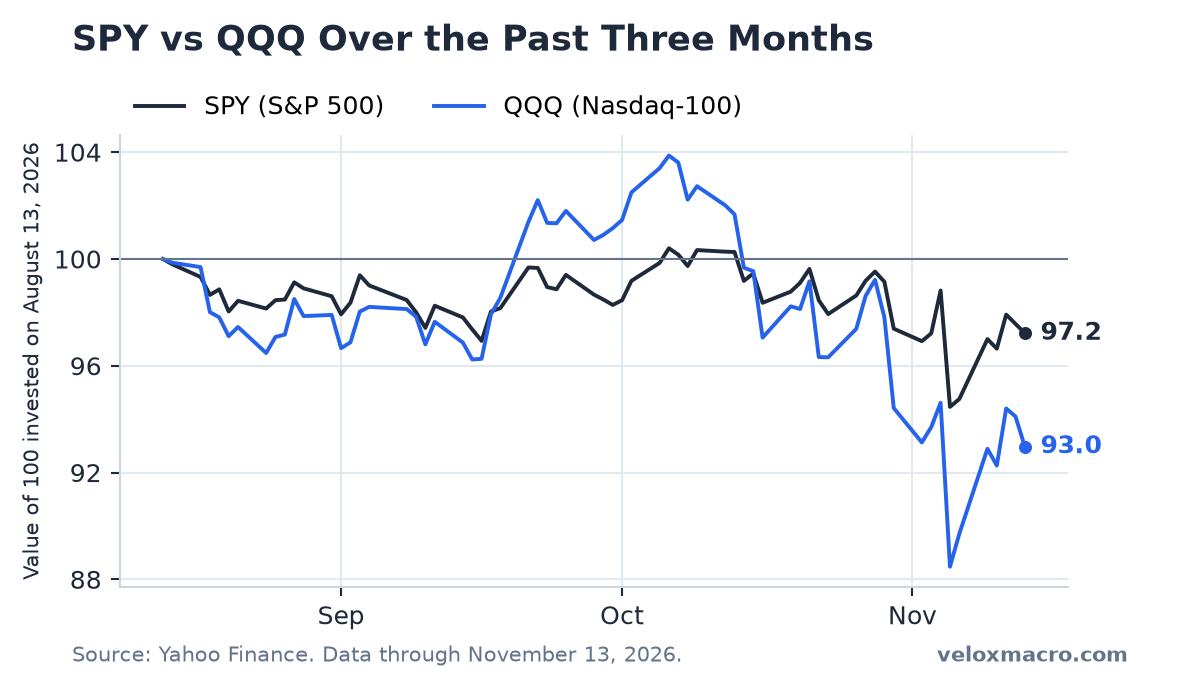
The week started with a sharp bounce. Monday lifted SPY from Friday’s 735.29 to 752.69 and QQQ from 656.10 to 679.35. Tuesday, the CPI release day, gave a little back. Wednesday’s Veterans Day session pushed SPY to 759.81 and QQQ to 690.38, the highs of the week. Thursday and Friday faded from those highs. SPY finished at 754.37 and QQQ at 679.89.
For the full week SPY gained 2.59% and QQQ 3.63%. That reverses last week’s pattern, when QQQ lagged. SPY is about 3.2% below its October 6 record of 779.09. QQQ is about 10.5% below its October 6 record of 759.66. Our SPY vs QQQ guide explains how to read a week when the Nasdaq-100 leads the rebound.
Mega-Caps: Apple at a Record, NVIDIA Still Falling
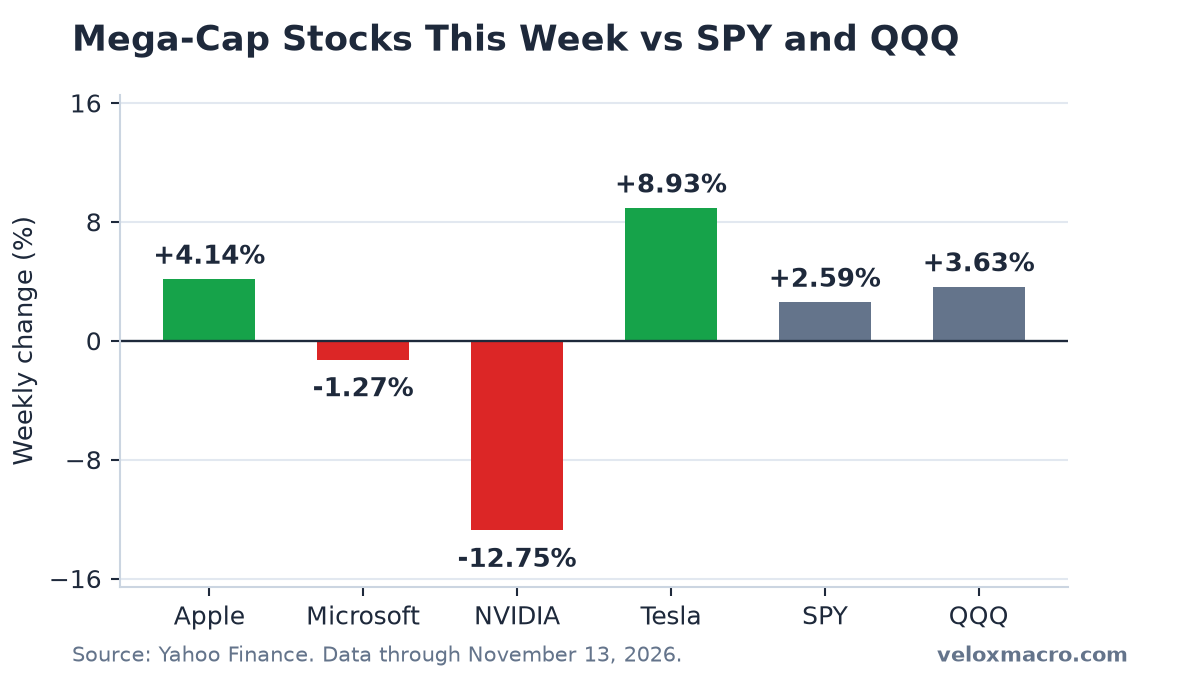
Apple and Tesla beat both indexes. NVIDIA did not.
- Apple rose 4.14% to 356.27. Wednesday’s 355.63 was a record. Friday’s close moved that high again.
- Tesla rose 8.93% to 390.22, recovering a large share of the prior week’s 10.40% drop.
- Microsoft fell 1.27% to 523.88, about 5.7% below its November 4 high of 555.80.
- NVIDIA fell 12.75% to 162.85. It dropped on four of the five sessions and is about 31.9% below its October 6 high of 239.24. QQQ can rise on a week NVIDIA falls when Apple and Tesla carry enough weight.
Our mega-cap guide keeps the week-by-week scorecard for these four names.
October CPI Lifted Yields Back Through 5%
October CPI rose 0.4% on the month, and core CPI rose 0.3%. The Bureau of Labor Statistics did not publish year-over-year rates because October 2025 CPI was never collected. September’s about 3.7% remains the last official annual reading. The fuller write-up is in the November 12 CPI and jobs analysis.
The 10-year yield started the week near 4.86% and finished Friday at 5.15%, up about 29 basis points on the week. Tuesday’s CPI morning took the market quote to 4.98%. Thursday closed at 5.10%, the first finish above 5% since October 28. Friday added another move to 5.15%. FRED’s official series was 5.10% on Thursday; there is no Wednesday print because the bond market was closed for Veterans Day.
The 2-year yield was 4.86% on Thursday, up from 4.51% on November 6 and about 98 basis points above the effective fed funds rate of 3.88%. The 10-year real yield was 2.86% on Thursday, up from 2.63% a week earlier. The breakeven inflation rate was 2.24% on Friday, almost unchanged from 2.23% on November 6. The backup in yields this week was again a real-yield move. The CPI-day session is covered in the November 10 yields analysis.
The VIX Cooled; Oil Stayed Near $89
The VIX fell 24.73% on the week, from 25.64 to 19.30. Monday’s drop to 19.92 took it back under 20 after the prior Thursday’s 28.18 spike. It briefly dipped to 17.49 on Wednesday, then settled near 19. That is still above the mid-teens of early October, and far below last week’s panic high. The Monday session is in the November 9 VIX analysis.
WTI fell 2.50% on the week to $88.56, after a Monday low near $86.85. Oil near $89 is softer than the late-October stretch above $100. Freddie Mac’s November 12 survey put the 30-year mortgage rate at 7.11%, down from 7.18%, even as the 10-year yield moved back above 5%. The dollar index rose 1.09% to 103.41.
October jobs are unchanged from last week: payrolls up 165,000 and unemployment at 4.1%. The Fed’s next decision with a new Summary of Economic Projections is December 9.
What to Watch
- Whether 5.15% holds. The 10-year is back above the October 28 decision-day close. The 2-year at 4.86% is nearly a full percentage point above the 3.88% funds rate.
- NVIDIA versus QQQ. A 3.63% week for QQQ with a 12.75% drop in NVIDIA is a split market, not a broad semiconductor rebound.
- The VIX around 19. Last week’s spike to 28.18 faded. A second move back through 25 would make this week’s calm look temporary.
- December 9. Projections return. October’s 0.4% monthly CPI and 4.1% unemployment are both in the book. Dates are on the economic calendar.
This is not financial advice.