A Soft Equity Week After Hotter Inflation
QQQ fell 5.52% in the week to October 16 and SPY dropped 1.97%. September CPI rose to 3.7% year over year, released on Wednesday, and the VIX closed Friday at 19.99, its highest since late July. Oil finished above $100, while the 10-year yield eased to about 5.10%.
Weekly changes run from the October 9 close to the October 16 close. This report was written on October 19 and uses only data available through Friday’s close.
Weekly Market Data (week ending October 16, 2026)
The stock table leads with the weekly change; Friday’s daily change is there for context. Macro rows use each indicator’s own as-of date. CPI and unemployment are the September FRED prints.
| Ticker | Week-Ending Close (USD) | Weekly % Change | Friday Daily % |
|---|---|---|---|
| SPY | 763.25 | -1.97% | -1.11% |
| QQQ | 709.80 | -5.52% | -2.50% |
| AAPL | 343.46 | +2.03% | +0.43% |
| MSFT | 529.05 | -1.13% | -1.93% |
| NVDA | 214.13 | -6.61% | -1.43% |
| TSLA | 354.72 | -7.31% | -2.13% |
| Indicator | Latest Value | As Of | Weekly % Change |
|---|---|---|---|
| 10-Year Treasury Yield (^TNX) | 5.10% | 2026-10-16 | -2.78% |
| 10-Year Treasury (FRED DGS10) | 5.10% | 2026-10-15 | — |
| VIX (CBOE Volatility Index) | 19.99 | 2026-10-16 | +34.70% |
| US Dollar Index (DX-Y.NYB) | 101.84 | 2026-10-16 | -0.36% |
| WTI Crude Oil (CL=F) | $101.41 | 2026-10-16 | +10.41% |
| Effective Fed Funds Rate (DFF) | 3.88% | 2026-10-15 | — |
| Unemployment Rate (UNRATE) | 4.2% | 2026-09-01 | — |
| CPI Index (CPIAUCSL) | 336.298 | 2026-09-01 | — |
SPY vs QQQ: Growth Took the Hit
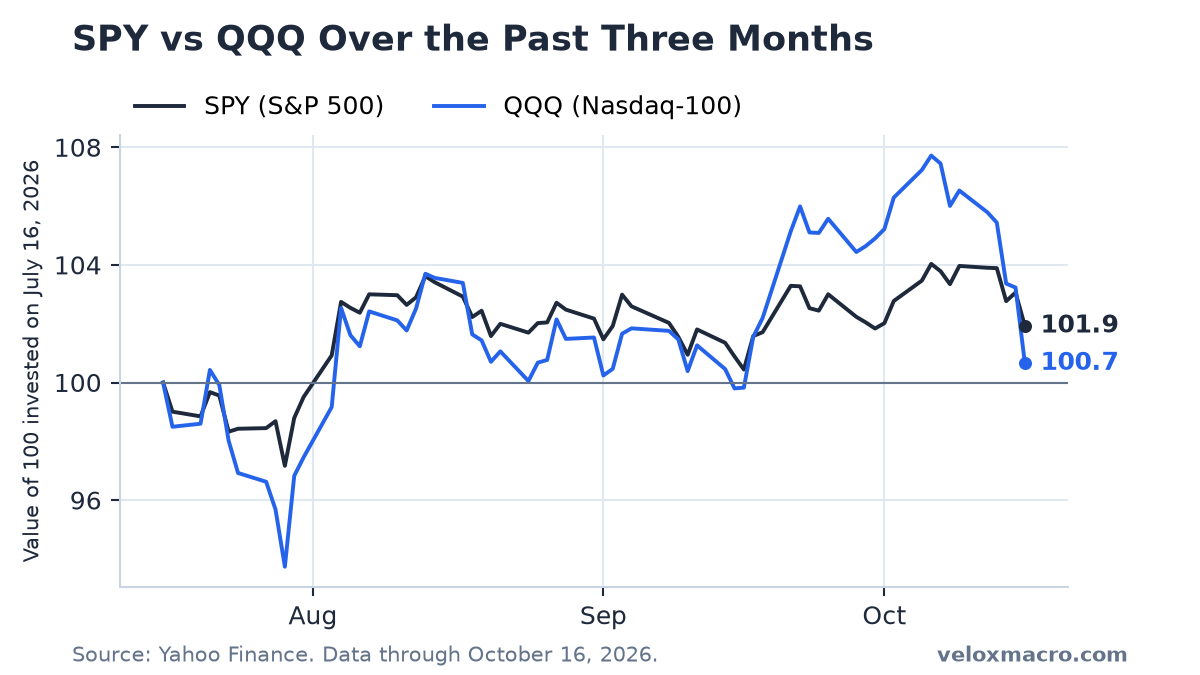
Last week SPY beat QQQ by about 0.9 percentage points. This week the gap widened the other way: SPY lost 1.97% and QQQ 5.52%, a spread of about 3.6 points against the Nasdaq-100 sleeve.
Monday and Tuesday were quiet. SPY barely moved near 778, and QQQ slipped gradually from 751 toward 744. Wednesday, the CPI release day, was the break: SPY fell 1.08% to 769.60 and QQQ fell 1.97% to 728.95. Thursday brought a small bounce in SPY (+0.28%) while QQQ stayed flat. Friday extended the damage, with SPY down 1.11% and QQQ down 2.50%.
That leaves SPY about 2.0% below its October 6 record of 779.09, and QQQ about 6.6% below its own record of 759.66. When QQQ falls much harder than SPY over a full week, the selling is usually concentrated in large growth names rather than across the whole market. Our SPY vs QQQ guide explains how to read that gap.
Mega-Caps: Only Apple Finished Higher
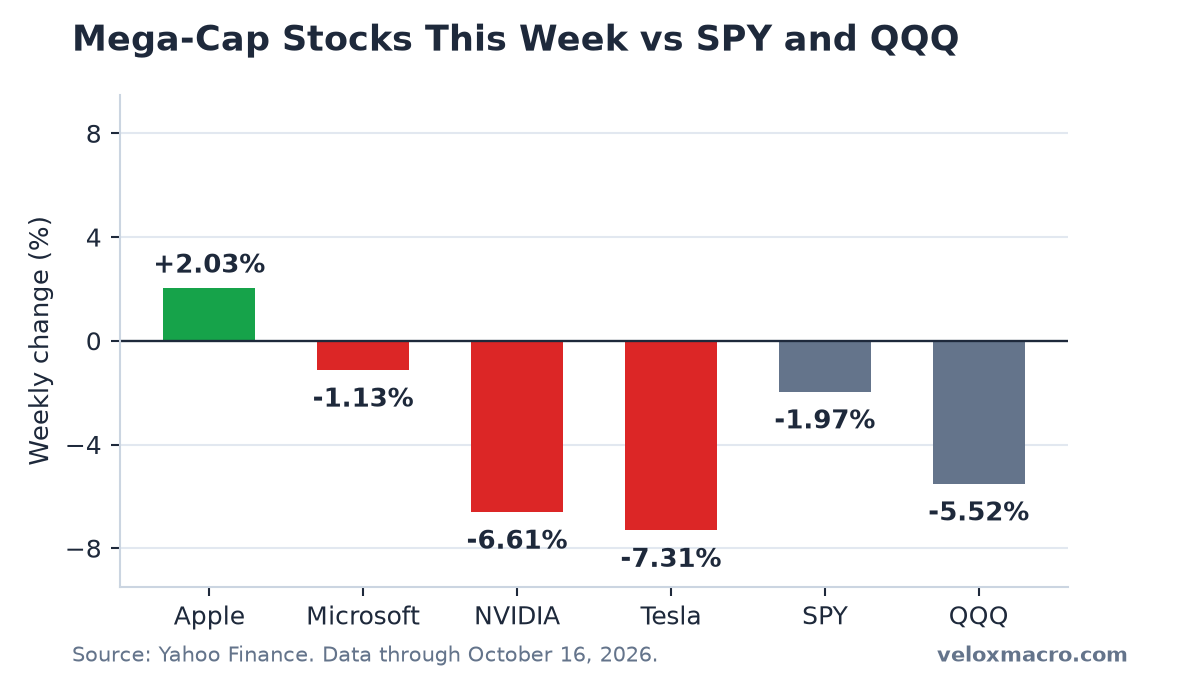
Of the four mega-caps we track, Apple was the only one green for the week.
- Apple gained 2.03% to 343.46, a new record close. It also set a record on Wednesday at 342.96 while the indexes sold off.
- Microsoft fell 1.13%. It had closed at a record 543.45 on Tuesday, then gave most of that back after CPI.
- NVIDIA dropped 6.61% to 214.13, about 10.5% below its October 6 record of 239.24.
- Tesla fell 7.31% to 354.72, the weakest of the four.
NVIDIA and Tesla together explain most of why QQQ lagged SPY so badly. Apple’s gain was not enough to offset them inside the Nasdaq-100. Our mega-cap guide keeps a week-by-week scorecard for these four names.
Inflation: September CPI at 3.7%
The main data of the week was Wednesday’s CPI report. The September index rose to 336.298, about 3.7% above a year earlier, up from 3.4% in August and the highest annual pace since May’s 4.2%. Core CPI, which leaves out food and energy, rose to about 2.6% from 2.5%. We covered the print in Friday’s CPI and jobs analysis.
Oil reinforced the inflation story. WTI rose 10.41% on the week to $101.41, reclaiming the $100 level. Energy feeds into headline CPI quickly, which is one reason the annual rate jumped more than core did.
Unemployment stayed at September’s 4.2%. No new jobs report came out this week. The next one is due November 6.
Rates: Yields Fell Through the Hot Print
The 10-year yield started the week near 5.24% and finished near 5.10%, down about 14 basis points. After Wednesday’s hotter CPI, yields kept easing rather than rising: the market quote was 5.19% on Wednesday, 5.09% on Thursday and 5.10% on Friday. FRED’s official series shows 5.10% on October 15.
That is the opposite of the usual “hot inflation, higher yields” pattern. Stocks and long yields fell together, which fits a risk-off week better than a pure inflation scare. The 10-year breakeven inflation rate stayed near 2.3%, so bond investors did not mark up long-term inflation expectations by much.
The effective fed funds rate held at 3.88%. Freddie Mac’s 30-year mortgage rate was still 7.40% in the October 15 survey, unchanged from the week before and the highest since November 2023. The next Fed meeting is October 27–28.
The VIX Climbs Toward 20
The VIX opened the week at 14.84 and closed Friday at 19.99, up 34.7%. That is the highest close since July 29 and just under the 20 line usually read as elevated stress. Most of the jump came on Friday (+21.5% on the day) after Wednesday and Thursday had already lifted it into the mid-16s.
A VIX near 20 after a week when QQQ lost more than 5% is consistent with investors paying more for protection. It is still far below this year’s high of 31.05 in March. The dollar index slipped 0.36% to 101.84 and was not the main story.
What to Watch
- The Fed meeting on October 27–28. September’s hotter CPI and soft payrolls are the backdrop. There is no new Summary of Economic Projections at this meeting.
- The VIX around 20. A close above 20 would mark a clear shift from the mid-teens range of early October.
- QQQ and NVIDIA versus their October 6 records. QQQ needs about 7% and NVIDIA about 12% to get back there.
- Oil above $100. Another week near this level would keep pressure on the next CPI report in mid-November.
This is not financial advice.